A High-Deductible Health Plan (HDHP) employer contribution is the money an employer deposits in employees’ health savings accounts (HSAs) to cover part of a high-deductible health plan’s deductible. An HDHP trades a lower premium for a higher deductible, so it saves money for the company and its employees only when the contribution covers enough of that deductible and employees can see what each plan would cost them over the year. That’s why HR should set the contribution and plan how employees will compare their options before deciding to offer an HDHP to employees.
What is an HDHP employer contribution?
An HDHP employer contribution is a deposit an employer makes into the HSA of each employee enrolled in its high-deductible health plan, often with one amount for single coverage and a larger one for family coverage. Employees own the account and can use the money for medical costs, including the care they pay for until they meet the deductible, the amount they owe each year before the plan starts paying. Two IRS rules shape what you can give:
- It counts toward employees’ limit. Employer contributions count toward the employee’s annual HSA limit, according to IRS Publication 969. The limit covers employer and employee deposits combined, so every dollar you put in is a dollar the employee can no longer add themselves. For example, if the limit is $4,000 and you contribute $1,000, your employee can contribute up to $3,000.
- It has to be fair across employees. If you make HSA contributions outside a cafeteria plan (a Section 125 plan, which lets employees pay for benefits with pre-tax pay), you have to give the same amount to every employee with the same type of coverage. For example, every employee on single coverage gets the same dollar amount, and every employee on family coverage gets the same dollar amount. You can also use the same percentage of the plan’s deductible for everyone in a group. If you don’t, according to IRS Publication 969, the IRS charges an excise tax (a penalty tax) of 35% of everything you contributed.
2027 HSA contribution limits and HDHP minimum deductible
For 2027, the IRS caps HSA contributions at $4,500 for self-only coverage and $9,000 for family coverage, according to IRS Revenue Procedure 2026-24, issued May 29, 2026. A plan counts as an HDHP only if its deductible is at least $1,750 for self-only coverage or $3,500 for family coverage.
| 2027 |
Self-only coverage |
Family coverage
|
| HSA contribution limit (employer and employee together) |
$4,500 |
$9,000 |
| HDHP minimum deductible |
$1,750 |
$3,500 |
| HDHP out-of-pocket maximum |
$8,700 |
$17,400 |
The out-of-pocket maximum is the most employees pay for covered care in a year, counting the deductible, copays, and coinsurance (their share of each bill after the deductible), but not premiums.
Why the HDHP employer contribution matters now
The HDHP employer contribution matters now because more employers are offering HDHPs, more employees are choosing them, and the contribution sets how much of the deductible those employees pay themselves. HDHPs were 23.59% of the plans employers offered through Healthee for 2026, up from 19.52% for 2025 and 16.66% for 2024, according to Healthee’s 2026 Benefits Divide report. In the same report, 26.56% of enrollees who compared plans in Healthee’s Decision Support Tool chose an HDHP for 2026, up 20.2% from 2025’s share. HSA adoption among eligible Healthee enrollees rose 42% year over year, according to the same report.
Most employees on an HDHP still have to pay part of their deductible themselves, because the employer’s HSA contribution rarely covers all of it. In 2026, workers in HSA-qualified plans (HDHPs that let employees open an HSA) had an average single deductible of $2,912, according to KFF’s 2026 Employer Health Benefits Survey.
That uncovered part of the deductible, which an HDHP employer contribution doesn’t cover, weighs most on employees who expect to use their plan: 54.56% of Healthee enrollees said they expected medium to high medical needs in the coming year, according to Healthee’s 2026 Benefits Divide report. Many weigh the gap against the PPO’s higher premium and see the PPO as the safer buy, even when the HDHP would cost them less over the year.
Does offering an HDHP save money?
Whether offering an HDHP to employees saves your company money depends on how many employees choose it. If only a few switch, you end up running two plans and still paying PPO premiums for nearly everyone. If employees choose it without understanding what they’ll owe, the unexpected medical bills come back to HR as questions and complaints.
How much should an employer contribute to an HSA?
An employer should contribute enough to an HSA that the HDHP’s total yearly cost comes in below the PPO’s for the employees it wants on the plan, including the ones who expect to need care. Workers in HSA-qualified plans received an average employer HSA contribution of $713 for single coverage and $1,346 for family coverage in 2026, according to KFF’s 2026 Employer Health Benefits Survey. Contributions are optional under IRS rules, so the right amount depends on your HDHP’s deductible, the premium difference between your plans, and how much care your employees use.
1. Measure the deductible gap for each coverage tier
The deductible gap is the deductible minus your HSA contribution. Take your HDHP’s deductible for single and family coverage, subtract the contribution you’re considering, and compare the single-coverage gap with KFF’s 2026 average of $2,222.
Compare your employees’ remaining deductible, meaning what’s left after your HSA contribution, with KFF’s $2,222 average. If you’re close to it, your employees face about what the average worker in an HSA-qualified plan faces. If you’re below it, employees who expect medical bills have a better reason to choose the HDHP.
2. Compare the HDHP’s total yearly cost with the PPO’s
Employees who compare premiums and deductibles separately often can’t tell which plan costs less, so compare one number instead:
Total yearly cost = the employee’s annual premium + expected out-of-pocket costs − your HSA contribution
Example: An employee with single coverage expects $2,000 of care. The HDHP deductible is $3,000, so a $750 HDHP employer contribution leaves $2,250 uncovered, close to KFF’s $2,222 average. The PPO costs $1,200 more in premiums but only $600 in copays.
|
PPO |
HDHP, no contribution |
HDHP, $750 contribution |
| Extra premium |
$1,200 |
$0 |
$0 |
| Care costs |
$600 |
$2,000 |
$2,000 |
| HSA contribution |
$0 |
$0 |
−$750 |
| Total |
$1,800 |
$2,000 |
$1,250 |
Without a contribution, the PPO is $200 cheaper. With $750, the HDHP is $550 cheaper, before tax savings.
Run this with your broker for a few typical employees:
- Someone who rarely sees a doctor
- Someone with a chronic condition
- A family expecting a baby
Then check your side: the premium you save per employee who switches, minus the contribution. If the HDHP wins only for the healthy employee, the contribution is too small or the HDHP isn’t ready.
3. Leave room for employees who want to save the maximum
Your HDHP employer contribution uses up part of each employee’s IRS limit, so they need to know how much room is left. In Healthee’s 2026 Benefits Divide report, 35% of enrollees chose the maximum HSA contribution. Many of your employees will want that number. Put it in your open enrollment communications in plain numbers: “Our $750 deposit leaves you $3,750 to contribute in 2027, or $4,750 if you’re 55 or older.” Employees can then set the right payroll deduction the first time and avoid going over the limit.
How to help employees choose the right health plan
Show each employee their estimated yearly cost under every plan before they enroll, counting the premium, their expected care, and your HDHP employer contribution. Plan summaries list the premium and deductible on separate lines, so employees see a big deductible and a small saving.
Younger employees are the hardest to win over: in 2024, Healthee users aged 18 to 29 were 90% less likely to choose an HDHP than users aged 30 to 44, according to Healthee’s 2025 Benefits Divide report. For those who want the mechanics explained, link Healthee’s HDHP vs PPO guide in your enrollment materials.
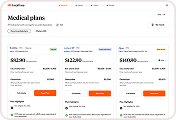
Tip: After you’ve run the numbers for a few typical employees, use an open enrollment software that has a decision support tool to help everyone. Healthee’s Plan Comparison Tool asks who an employee is covering, what care they expect, and which doctors they see. It then suggests the top 3 medical plans and estimates each plan’s yearly cost, including the premium, your HSA contribution, and a prediction of care they didn’t plan for. Employees also see a best case (the premium alone) and a worst case (the out-of-pocket maximum plus the premium), so they know the most the HDHP could cost them.
Make benefits easier for you and your employees
After open enrollment, check who enrolled in the HDHP to see whether your HDHP employer contribution worked.
If the enrollees are mostly in one coverage tier (for example, single) or one age group, rerun the yearly cost comparison for the tiers and ages that stayed on the PPO. Start with how much of their deductible your contribution leaves uncovered.
If employees across ages and coverage tiers chose the HDHP, your contribution and your plan comparison did their job.
Offering an HDHP to employees saves money only for those who enroll in it, so everyone choosing a plan needs to see their own numbers first. Healthee shows each of them an estimated yearly cost for every plan, your HSA contribution included, so they can pick the plan likely to cost them least.